As reported on November 6, 2026, TeraWulf had a credit-support agreement for anticipated debt financing at its Justified data-center campus—but had not disclosed the size or terms of the proposed project debt. For a company shifting from Bitcoin mining toward AI infrastructure, the operational question was whether it could finance construction and deliver capacity before the new lease began generating revenue.
What changed in November
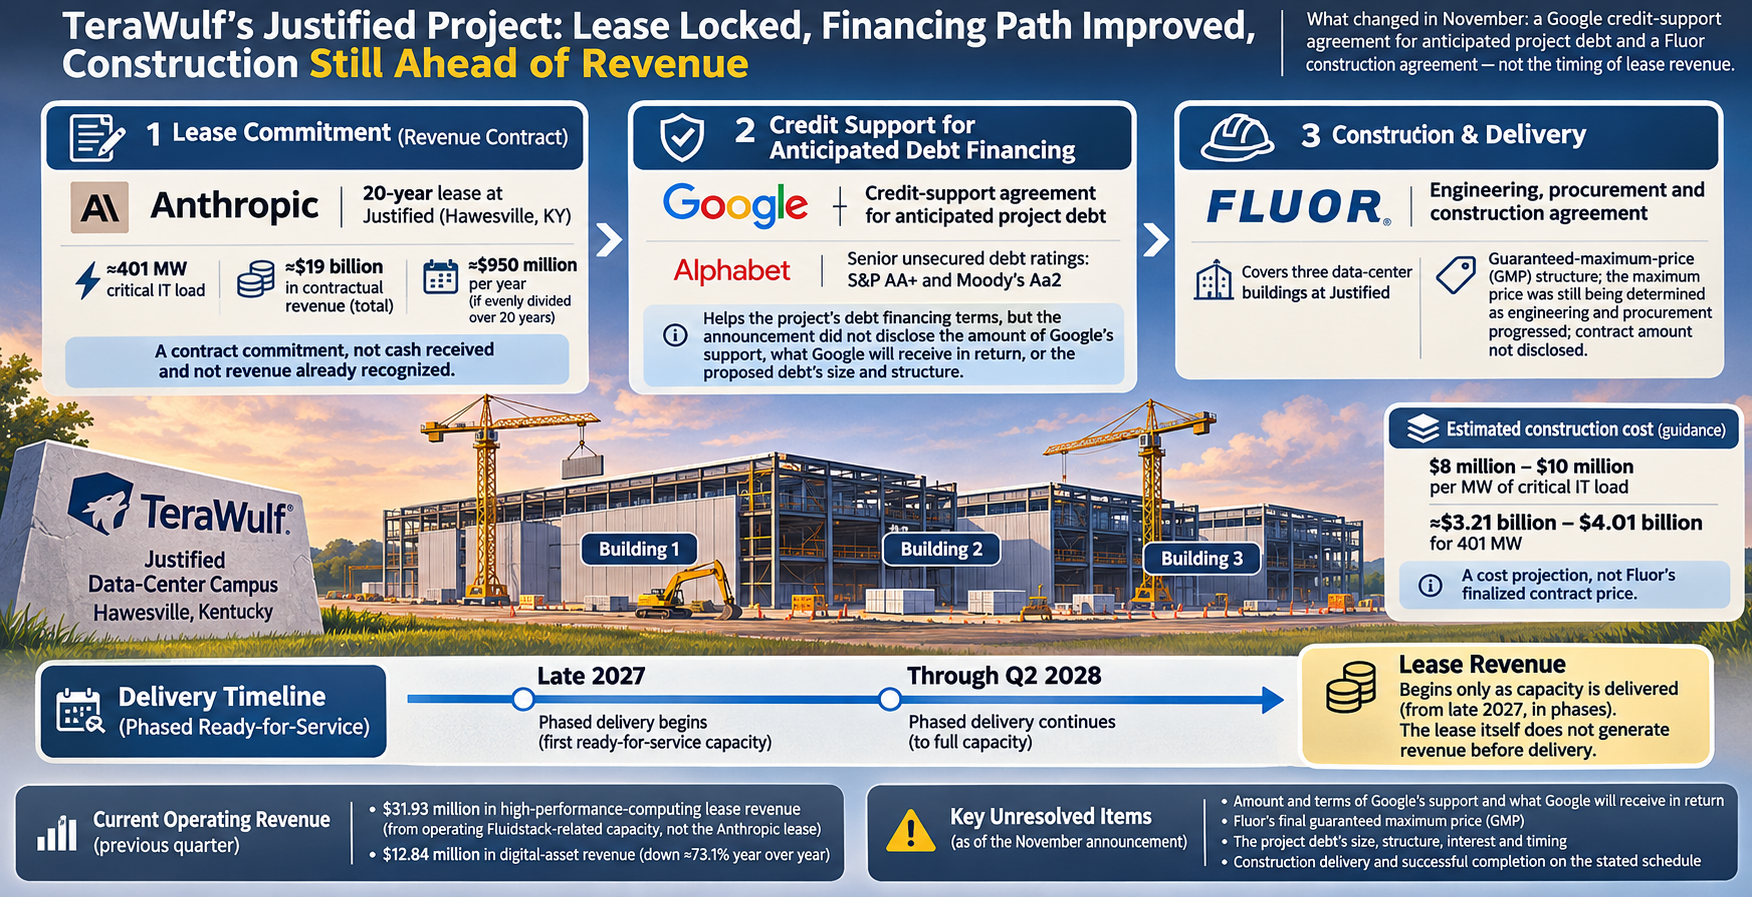
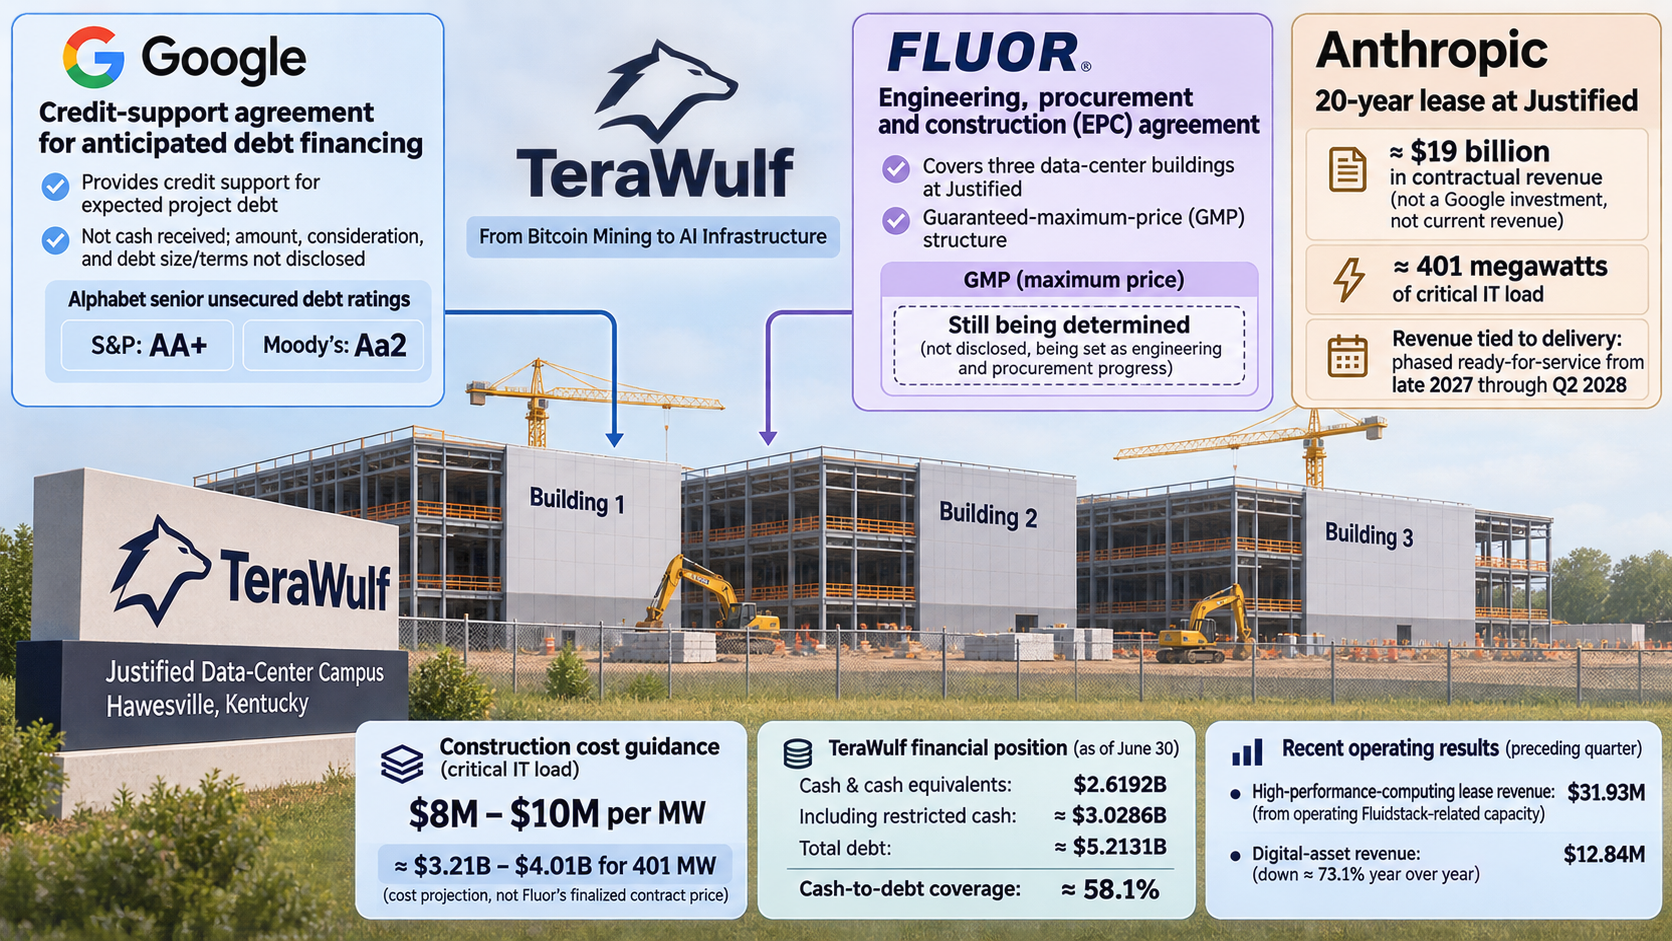
TeraWulf’s November 4 announcement said it had signed a credit-support agreement with Google LLC and a formal engineering, procurement and construction agreement with Fluor Enterprises. The Fluor contract covers three buildings at Justified in Hawesville, Kentucky, and uses a guaranteed-maximum-price structure. That maximum price was still being determined as engineering and procurement progressed; the contract amount was not disclosed.
The Google agreement concerns anticipated debt financing, not cash already received. The announcement did not disclose the amount of Google’s support, what Google would receive in return, or the proposed debt’s size and structure. It cited ratings of AA+ from S&P and Aa2 from Moody’s for Alphabet’s senior unsecured debt. Those ratings help explain why credit support could matter to financing terms, but they do not establish what this project will borrow or pay in interest.
Lease commitments are not current revenue
A separate, July 6 agreement set out a 20-year Anthropic lease associated with approximately $19 billion in contractual revenue and about 401 megawatts of critical IT load at Justified. The $19 billion is neither a Google investment nor revenue already recognized. Dividing it evenly across 20 years gives roughly $950 million a year, but that arithmetic is not a delivery or revenue forecast.
The November reporting put phased ready-for-service delivery from late 2027 through the second quarter of 2028. That is later at the far end than the July description, which anticipated initial capacity in the second half of 2027 and full capacity in early 2028. Revenue from the Anthropic capacity therefore depends on delivery, rather than on the signing of either agreement.
TeraWulf’s preceding quarter already included $31.93 million in high-performance-computing lease revenue, from operating Fluidstack-related capacity—not the Anthropic lease. Its $12.84 million in digital-asset revenue was down about 73.1% year over year. The two revenue streams should not be counted as evidence that Justified is operating.
The construction and financing gap
TeraWulf’s disclosed construction-cost guidance of $8 million–$10 million per megawatt of critical IT load implies approximately $3.21 billion–$4.01 billion for 401 megawatts. That is a cost projection, not Fluor’s finalized contract price. In the first half of 2026, cash outflow for purchases and prepayments of plant and equipment was $1.3785 billion; that historical spending does not establish the remaining cost or pace of work at Justified.
As of June 30, the company reported $2.6192 billion in cash and cash equivalents, or about $3.0286 billion including restricted cash, against approximately $5.2131 billion in total debt. The distinction matters: restricted cash is not interchangeable with unrestricted cash available for construction.
Google had supported earlier Fluidstack-related arrangements in August 2025, with $3.2 billion in aggregate guarantees associated with 73.5 million warrants across two rounds. Those terms provide a precedent, not the terms of the November 2026 agreement. The unresolved items were the new support and warrant terms, Fluor’s final maximum price, the project debt’s terms and timing, and construction delivery.